There were two interesting comments made during the Devon conference call today:
David Hager, Executive V.P. of E&P - "While it's in the very early stages of the evaluation of our position, we
are very encouraged that the Cline Shale with be a highly economic oil play."
John Richels, CEO - "Current production is less than 500 bod that we'd be conveying." This is regarding to current production on the JV acreage.
It appears that the lands conveyed to Sumitomo are basically undeveloped and they paid $7,200/acre for undeveloped Cline Shale land. A portion of Devon's land is adjacent to Lynden Energy Corp.'s Mitchell Ranch and that may help explain today's runup in Lynden's stock price.
Wednesday, August 1, 2012

Devon Energy/Sumitomo $1.4 Billion JV in Cline Shale and Midland-Wolfcamp Shale
Devon Energy announced a $1.4 billion joint venture with Sumitomo Corporation. Sumitomo will invest $1.4 billion in exchange for 30 percent of Devon's 650,000 acres in the Cline Shale and Midland-Wolfcamp Shale. This deal is equivalent to $7,200/acre!
The deal is generating a lot of industry attention. Wunderlich Securities expects to see more JV's in the Permian Basin as this deal is "the first block buster JV in the Midland Basin and we expect more to come".
There is a lot of drilling activity in the Permian Basin and Lynden Energy has significant holdings in both the Wolfberry and Cline Shales. Lynden's West Martin/Wind Farms project and Tubb project include 6,509 net Wolfberry acres and is now producing over 900 boe/d per the company's latest release. The core area (West Martin/Wind Farms and Tubb) can be valued at $25,000/acre to $30,000/acre given the amount of current development valuing it at $150 million to $200 million.
Lynden's Mitchell Ranch acreage is in the heart of the Cline Shale, in fact Devlon has significant Cline holdings adjacent to it. Should one value Lynden's 34,150 net Mitchell Ranch acres at $7,200/acre, LVL's market cap would soar!
With the increased industry attention to the Permian Basin and the Cline Shale, it is likely that larger companies are either looking at Lynden or will be looking at Lynden. Lynden is a unique company as it's one of the few small companies in the basin that has significant acreage. Lynden is sitting on a great asset that is in the heart of the Permian activity and is in a great position to take advantage of the recent JV activity.
Tuesday, July 3, 2012
Breitburn Energy Closes Permian Acquisition
BreitBurn Energy Partners L.P. closed on their Permian Basin Wolfberry acquisition. The price per acre metric was $47,826/acre. Of additional interest is that it was disclosed that CrownRock LP was the seller of one of the properties for $70 million. CrownRock is the working interest partner in all of Lynden Energy's projects.
Friday, May 11, 2012
Lynden Acreage Map
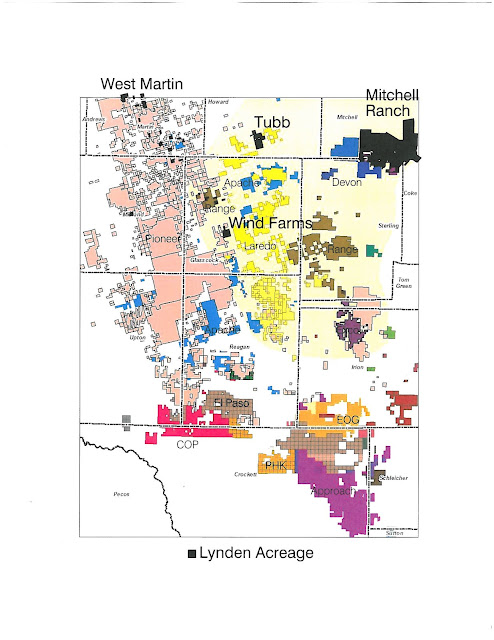
As you can see from the above map (LVL lands shown on map taken from Laredo's recent presentation), Lynden Energy Corp. has acreage located within the heart of the Wolfberry play with all of the large Wolfberry players surrounding them.
Given the two recent Permian Basin acquisition metrics of $38,600/acre and $47,826/acre, it's possible that Lynden could sell portions of their acreage for similar amounts. Here are valuations of each of Lynden's prospect areas based upon the recent transactions:
West Martin, 2,746 net acres @ $43,000/acre = $118 million
Wind Farms, 1,095 net acres @ $43,000/acre = $47 million
Tubb, 2,469 net acres @ $43,000/acre = $106 milllion
Lynden's Mitchell Ranch prospect area is within Devon Energy's delineation of the Cline Shale. Valuing that land at $5,000/acre equals $171 million (34,150 net acres).
Recent transactions are continually validating Lynden's land as viable Wolfberry acreage. With companies scrambling to assemble Wolfberry acreage positions, Lynden has a tremendous opportunity to capitalize!
Thursday, May 10, 2012
BreitBurn Energy Partners enters Permian Basin, another great Wolfberry comp! $47,826/acre!!!
BreitBurn Energy Partners L.P. signed two agreements to acquire Permian Basin Wolfberry properties. The combined price is approximately $220 million. The assets include:
- Net production of 2,100 boe/d (56% oil)
- Estimated proved reserves of approximately 9.5 mmboe
- Net acreage position of 4,600 acres
This is a great comp for Lynden Energy! The price per acre metric for these transactions is $47,826/acre and $104,762 per flowing boe/d.
- Net production of 2,100 boe/d (56% oil)
- Estimated proved reserves of approximately 9.5 mmboe
- Net acreage position of 4,600 acres
This is a great comp for Lynden Energy! The price per acre metric for these transactions is $47,826/acre and $104,762 per flowing boe/d.
Wednesday, May 2, 2012
Comments about Permian values and Cline
The latest issue of A&D Watch Weekly was released today and included some exciting comments. An article about Permian Basin values stated that there is still great deal price upside in the basin. The article states further that the Permian has a lot of room to go up due to the potential of several stacked payzones and that development is easier in the Permian than most other basins due to the ease of doing oil development in Texas and the few surface obstacles.
Ward Polzin, head of A&D for Tudor Pickering, Holt & Co. Securities, Inc., was quoted in the article saying that the Cline shale play is the "next new hot thing, no question about it," and that the "Cline is the real thing."
Monday's release regarding the Eagle Energy Trust acquisition and $38,600/acre valuation backs up the comments from the A&D article.
Monday, April 30, 2012
Eagle Energy announces Midland acquisition, $38,600/acre!!!
Eagle Energy Trust announced that they have entered into an agreement to acquire a 92.5% interest in 3,175 gross (2,937 net) acres of land near Midland. The purchase price is $113.4 million which equals a transaction price of $38,600/acre!
The asset includes 600 boe/d of production as of March and the company expects production to be approximately 1,000 boe/d by the end of 2012 (sound familiar...) Estimated proved plus probable reserves is approximately 10.2 mmboe.
"These long life, high netback assets represent a solid, low risk entry-point for Eagle into one of the most prolific and well-established oil weighted basins in North America. We believe that the Permian Basin will form a new strong core area of future operations for Eagle. It is one of North America's most productive oil-weighted basins and has demonstrated, on a recurring basis, the addition of new reserves horizons and enhanced exploitation of existing horizons in the multi-zone stacked pay resource," says Richard Clark, President and CEO of Eagle Energy Trust.
As a comparison, on April 4 Lynden Energy Corporation announced over 500 boe/d after royalty net production and has estimated end of 2012 production of approximately 1,000 boe/d. Most of this production is located within their West Martin and Wind Farms Wolfberry projects where Lynden owns 3,841 net acres and has 9.8 mmboe of proved plus probable reserves as of 6/30/11. The Eagle Energy Trust asset acquisition has very similar numbers to Lynden's West Martin and Wind Farms projects. Should one value Lynden's West Martin and Wind Farms acreage on a similar acreage metric as the Eagle Energy transaction, those lands alone would be valued at approximately $148 million which far exceeds the company's current market cap. After adding in Lynden's Tubb and Mitchell Ranch acreage, one can conclude that Lynden has incredible potential.
Subscribe to:
Posts (Atom)


